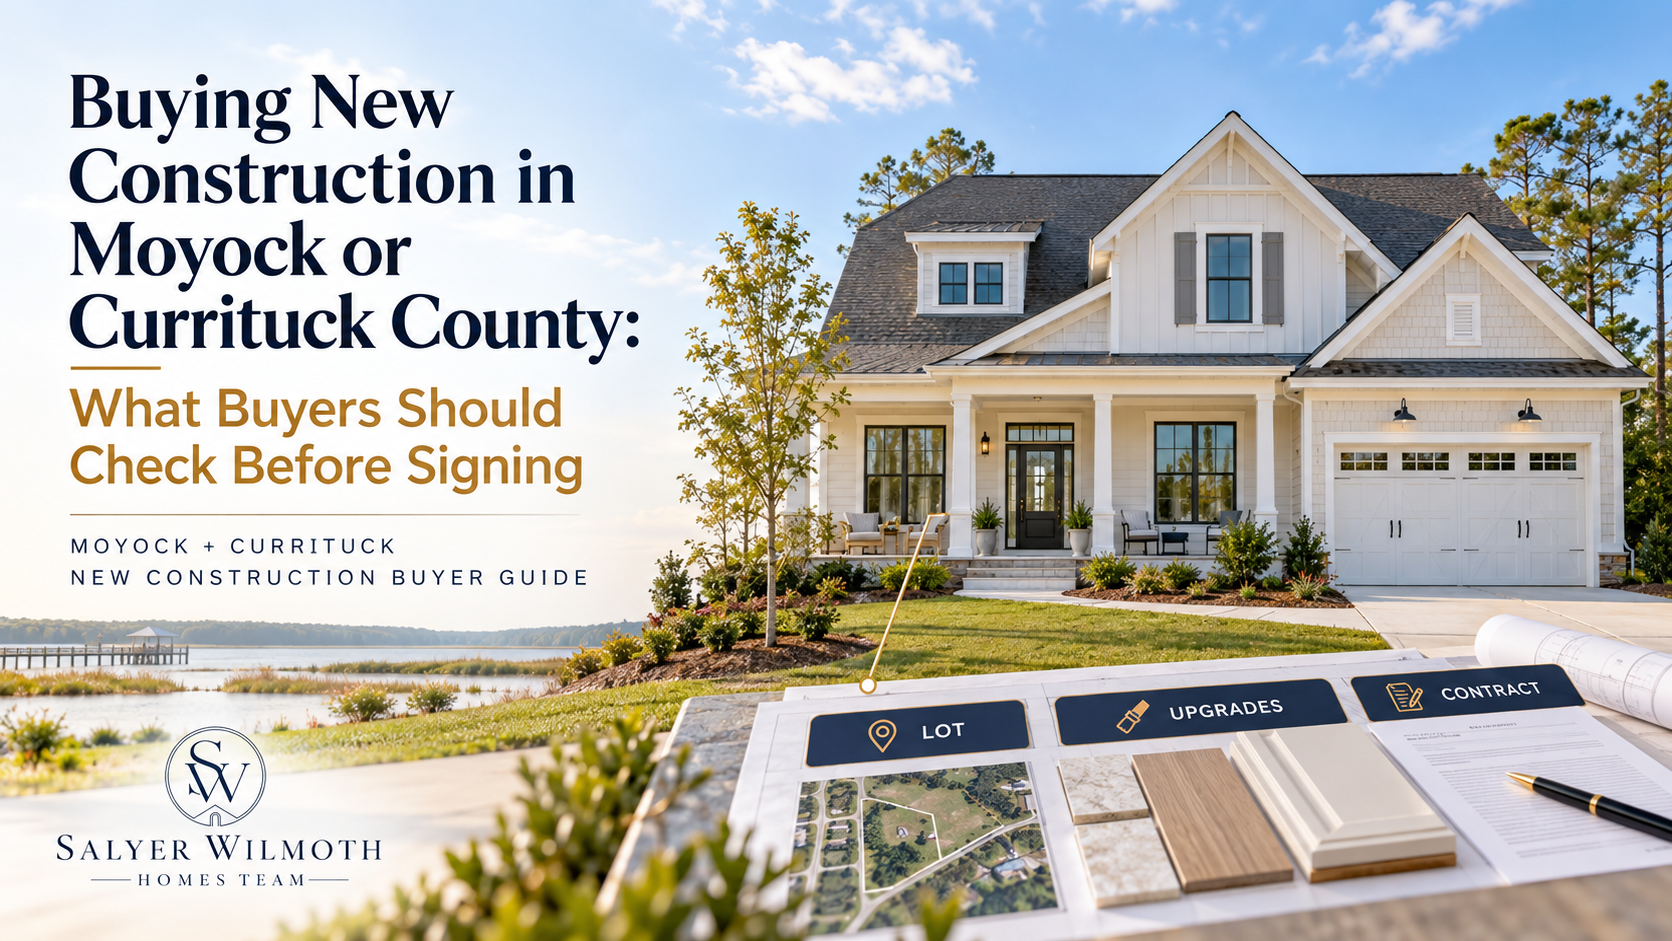
Buying New Construction in Moyock or Currituck County: What Buyers Should Check Before Signing
TL;DR
Buying new construction in Moyock or elsewhere in Currituck County is not simply a resale purchase with a newer house attached to it. Before signing, buyers should understand exactly which contract is being used, when earnest money or construction-related funds become committed, what opportunities they have to investigate the lot and financing, which plans and specifications actually control the build, how upgrades and change orders affect the final price, what the builder means by an advertised “base price,” whether a lot premium or community fees apply, how construction delays are handled, when independent inspections can occur, what warranty the buyer will actually receive, and what happens if the completed home does not appraise at the final contract price. North Carolina’s current new-construction forms make many of these issues explicit: Form 800-T uses a pre-construction evaluation period and can include earnest money and construction fees; it requires detailed plans and specifications to be incorporated into the contract and uses written change orders for material changes, while the current New Construction Addendum is generally aimed at homes that are much further along. Currituck County adds property-specific questions involving permits, floodplain requirements, utilities, septic or sewer availability, roads, and association costs. The safest approach is to treat the model home and builder price sheet as the beginning of the conversation—not the definition of what you are actually buying. NC REALTORS®
Start With the Contract, Not the Model Home
New construction is designed to make the buying process feel exciting.
You tour a decorated model, choose a floor plan, look at cabinet finishes, imagine the backyard, and start thinking about where the furniture will go.
But the part that controls what you actually receive is not the model.
It is the contract.
North Carolina currently has a specific Offer to Purchase and Contract—New Construction, Form 800-T, designed for situations in which the seller or a contractor engaged by the seller will construct a home on land owned or to be owned by the seller and then convey the completed property to the buyer. NC REALTORS® describes it as both a construction agreement and a contract for the eventual sale of the land and home.
The current 2026 forms guidance also draws a practical distinction between Form 800-T and the New Construction Addendum used with the ordinary residential contract. If drywall has not yet been completed, Form 800-T is generally the form more likely to fit; if drywall has already been completed, the revised New Construction Addendum may be the better fit.
And a builder may present a different contract entirely.
That is where I would slow the process down.
Before a buyer gets emotionally invested in the lot, selections, or incentive package, I want to know what document will govern the transaction and which protections, deadlines, deposits, warranties, inspection rights, and remedies are actually written into it.
A polished sales presentation cannot substitute for those terms.
New Construction Does Not Always Use the Same Due Diligence Structure as a Resale
This is one place where buyers who already understand North Carolina resale transactions can still be surprised.
Our guide to North Carolina Due Diligence Fee vs. Earnest Money for Moyock and Currituck Buyers explains how the commonly used resale contract treats the due diligence fee, earnest money, and due diligence deadline.
A true new-construction transaction under Form 800-T is structured differently.
The current form provides for earnest money and may also require Construction Fees paid to the seller at specified stages. It also uses a defined Pre-Construction Evaluation Period, during which selected conditions involving financing, insurance, roads, soil, utilities, septic, wells, flood issues, zoning, environmental permits, and other matters may be investigated depending on what the parties include in the agreement.
That means a buyer should not walk into a sales office expecting every new-construction contract to function exactly like a Form 2-T resale offer.
And the amount of money at risk deserves careful attention.
Form 800-T itself warns buyers to think seriously about how much they are willing to pay in Construction Fees because even when a buyer is legally entitled to a refund after a seller's material breach, actually recovering that money may still become difficult, time-consuming, or costly if the seller does not voluntarily return it.
If a builder uses its own contract instead of the standard form, the terminology and refund provisions may be different again.
I would want those answers before the deposit is wired, not after.
The Advertised Base Price Is Only the Starting Number
A sign advertising homes “from” a certain price does not necessarily tell you what the house you want will cost.
The relevant number is the price of your lot + your floor plan + your structural choices + your selections + any premiums + applicable fees and changes under the actual agreement.
That difference can become significant.
A particular lot may carry a premium because of its size, location, view, cul-de-sac position, privacy, or other characteristics. A floor plan may have several elevations. The kitchen shown in the model may use upgraded cabinetry, countertops, appliances, flooring, lighting, hardware, trim, or plumbing fixtures. An additional bedroom, screened porch, covered patio, fireplace, alternate primary-bath layout, or upgraded garage may change the price again.
The current Form 800-T addresses this problem by requiring the agreed Plans and Specifications to be listed and attached, and it specifically incorporates items such as site plans, house plans, structural drawings, and other specifications into the contract. The form also states that significant deviations and buyer-requested changes are to be documented through written Change Orders that can alter the purchase price, construction fees, allowances, and specifications.
That is exactly how I want buyers to think about the builder's sales materials:
What is actually contractual?
If the model has quartz counters, a tiled shower, an appliance package, irrigation, upgraded landscaping, blinds, additional lighting, or a larger patio, do not assume your house includes those items simply because you saw them during the tour.
The contract and attached specifications should answer the question.
Treat Upgrades Like Financial Decisions, Not Just Design Decisions
The design center is where budgets can quietly move.
An extra few thousand dollars here and another few thousand there may seem manageable when each upgrade is discussed separately.
By the time flooring, cabinets, counters, electrical selections, fixtures, structural options, and lot premiums are added together, the finished contract price can look very different from the number that first attracted the buyer to the community.
The current North Carolina new-construction form specifically recognizes allowance items and written change orders. It also warns buyers that timely decisions about selections and changes matter because buyer-requested changes and delays in choosing allowance items can affect the construction schedule.
One thing I would want to track is the running contract price, not merely the amount spent at the design center.
Every material change should answer three questions:
What does this add to the price?
Does it change the construction timeline?
And does the lender know the new number?
That last question becomes increasingly important as upgrades accumulate.
A $20,000 Upgrade Does Not Guarantee $20,000 in Appraised Value
This is where design preference and financing can collide.
You may genuinely value an upgraded kitchen, screened porch, premium lot, oversized shower, or high-end flooring enough to pay extra for it.
An appraiser is not required to assign the same dollar-for-dollar value to those choices.
The appraisal ordered for a financed purchase is performed for the lender, and North Carolina Real Estate Commission guidance emphasizes that brokers may provide relevant information to the appraiser but may not attempt to influence the appraiser's value conclusion.
That means the buyer should ask the lender early how the appraisal will be handled, when it will be ordered, and what happens under the signed contract if the final purchase price exceeds the lender's appraised value.
Do not assume that every builder upgrade automatically finances itself simply because it was added to the purchase agreement.
This is especially worth discussing when the price has moved substantially above the subdivision's original base price.
If we are comparing two build options for a buyer, I would look at the upgrades in two ways at once: Will you enjoy and use them? And are you comfortable paying for them even if the market does not give you every dollar back?
Builder Incentives Are Valuable Only After You Understand the Tradeoff
Builders may advertise closing-cost assistance, rate incentives, design-center credits, appliance packages, upgrade allowances, or other promotions.
Those can be meaningful.
But an incentive should never end the comparison.
The Consumer Financial Protection Bureau specifically reminds new-construction buyers that builders may have an affiliated or preferred mortgage lender, but buyers do not have to use that lender and have the right to shop for another mortgage. CFPB also recommends comparing actual Loan Estimates because lender credits can lower upfront costs while sometimes being paired with a higher rate.
So if the builder says:
“Use our lender and receive $12,000 toward closing,”
the next question is not simply:
“Where do I sign?”
It is:
“What does the loan cost with the incentive compared with the best realistic alternative?”
Compare interest rate, points, lender fees, monthly payment, cash to close, and any restrictions on how the incentive can be used.
The builder's incentive may still be the best deal.
Now you will know why.
Have Your Own Inspection Even Though the County Inspects the House
A new house should absolutely be built to code.
That does not make an independent inspection unnecessary.
Currituck County performs governmental inspections during construction, and its permitting system allows permits and inspection results to be reviewed online. The county notes that the inspections required depend on the permit and type of project.
Those inspections serve an important regulatory purpose.
An independent home inspector serves the buyer.
The North Carolina Real Estate Commission expressly advises that even buyers of newly constructed homes should have home inspections and notes that licensed inspectors may recommend additional specialist evaluations when appropriate.
The standard Form 800-T likewise gives the buyer a contractual mechanism to inspect construction at reasonable times before closing or possession and to raise substantial deviations from the plans and specifications.
Depending on how far along the home is when you contract and what access the agreement allows, useful inspection points may include a pre-drywall or rough-in inspection and a final independent home inspection before settlement.
Do not confuse that final independent inspection with the builder's punch-list walkthrough.
Both can be useful, but they are not the same exercise.
Our broader article on home inspection findings and how buyers evaluate them is Virginia-contract specific, so the contractual procedures are different, but the practical principle carries over: the goal is to distinguish cosmetic items from conditions that materially affect safety, function, future expense, or value.
The Punch List Is Not the Same as a Perfect House Before Closing
New construction buyers often expect every cosmetic item to be corrected before settlement.
The actual contract may say something more nuanced.
Under the current Form 800-T, the seller schedules a pre-completion inspection with the buyer so the parties can identify visible workmanship and material deficiencies for a written punch list. The form requires the seller to correct those items, but once the home reaches the contractual definition of substantial completion, the seller's failure to correct a punch-list item before settlement does not automatically give the buyer the right to delay settlement. The builder's correction obligation continues after closing.
That is a detail buyers should understand long before the final walkthrough.
A paint touch-up and a major construction deviation should not be treated as the same issue.
And if the builder is using a proprietary contract rather than Form 800-T, read its punch-list provisions carefully because the timing and remedies may differ.
“Completion Date” Does Not Always Mean “Guaranteed Move-In Date”
Building a home involves more moving pieces than buying an existing house.
Weather changes.
Materials get delayed.
Inspections need to be scheduled.
Selections arrive late.
A buyer requests a change order.
Utilities are not ready.
A permit takes longer than anticipated.
That does not mean a builder should have an unlimited schedule.
It means the contract needs to explain what happens when construction runs late.
Under Form 800-T, Substantial Completion generally requires the dwelling to be sufficiently complete and habitable, broom-clean, covered by a certificate of occupancy, and down to remaining punch-list items. The form then generally sets settlement within 14 days after substantial completion unless the parties agree otherwise. Certain construction delays contemplated by the contract can extend the substantial-completion timeframe, in specified circumstances, by a reasonable period of up to 60 days.
A builder's own contract can be different.
This matters tremendously if you are selling another home, ending a lease, arranging a military move, locking a mortgage rate, scheduling movers, or expecting school enrollment around a projected closing date.
I would plan around the contractual timeline, not the optimistic date mentioned during the first sales appointment.
Verify What “Warranty” Actually Means
A new house does not automatically mean unlimited builder responsibility after closing.
And North Carolina does not have a blanket law requiring every builder to give every new-home buyer a one-year written builder warranty simply because the property is new. NC REALTORS® has specifically cautioned against that common assumption.
The contract matters.
Form 800-T currently includes a one-year warranty of construction unless the parties replace it with an attached written warranty. It also addresses transferable manufacturer warranties for components.
The New Construction Addendum used with the resale contract also contains an express builder warranty, which NC REALTORS® has described as an important protection for completed or nearly completed new homes.
If the builder presents its own warranty booklet, read it before closing.
Look at when the warranty starts, what is excluded, how claims must be submitted, whether there are short reporting windows for particular items, who decides whether something is warrantable, and which manufacturer warranties cover appliances, HVAC equipment, roofing, windows, or other components separately.
“Builder warranty included” is not enough information to evaluate the protection.
Currituck County Lot Conditions Still Matter Even in a New Subdivision
New does not mean property-specific due diligence disappears.
Currituck County's current new-construction framework still involves permits, local inspections, utility conditions, floodplain rules, and—in some locations—septic or well questions.
For a lot in a Special Flood Hazard Area, Currituck County states that new construction must comply with its floodplain-development requirements, including additional freeboard requirements above the FEMA base flood elevation.
Water and sewer arrangements can also vary.
Currituck's water department notes that new water connections can involve impact fees and that buyers or builders should verify service eligibility and whether the applicable fee has already been paid. The county also maintains a regional wastewater system serving parts of Moyock, while other properties or developments may operate differently.
That means the sales-office answer “utilities are available” deserves one more question:
Which utilities, under what arrangement, and which connection or system costs are already included in my price?
The same principle applies to streets.
Form 800-T specifically gives buyers an opportunity during the pre-construction evaluation period to investigate whether the street is public or private, whether it has been accepted for public maintenance, and who is responsible when it has not.
For buyers considering larger lots or communities where private wastewater systems are involved, our guide to buying a home with well or septic in Chesapeake and Northeast North Carolina goes deeper into those systems.
Read the HOA Documents Before You Choose the Lot
A neighborhood may look finished long before the association's finances, responsibilities, and future costs are obvious to a buyer.
If the home will belong to an owners' association, verify the regular assessment, what that assessment covers, any buyer contribution or initiation fee, architectural restrictions, maintenance responsibilities, and known or planned special assessments.
North Carolina law generally requires disclosure of association obligations for covered residential transfers, including regular assessments and approved special assessments, but first sales of never-inhabited dwellings have a statutory exemption from the ordinary residential disclosure framework.
That does not mean HOA questions should disappear from a new-home transaction.
Form 800-T itself contains association provisions, and NC REALTORS® explains that when the form is used without deleting its association-disclosure language, the seller must provide the specified association disclosure addendum if an owners' association applies. A builder using a different contract may handle that disclosure differently.
If I were helping a buyer choose between two Moyock lots in the same community, I would not look only at the premium and backyard orientation.
I would also want to understand what the governing documents allow you to do with that lot after closing.
A fence, detached shed, pool, boat storage, exterior modification, or future addition can matter just as much as the finishes you are choosing today.
Make Sure “Included” Means Included in Writing
This is one of the simplest new-construction rules and one of the easiest to ignore.
If something matters enough that you would be upset not to receive it, make sure the contract documents address it.
Form 800-T's entire-agreement provision makes clear that the written contract and attached documents control the agreement and that changes, additions, and deletions—including changes to plans and specifications—must be in writing and signed.
So when the builder representative says:
“That appliance package should be included.”
“That lot normally comes fenced.”
“We usually add the blinds.”
“The landscaping package is probably the upgraded one.”
Do not build your purchase decision around “should,” “usually,” or “probably.”
Get the specification.
This is also why buying new construction without independent representation can create a different risk than buyers expect. The builder's sales representative is there to sell the builder's property and operate within the builder's process. If you want a broader explanation of what buyer representation actually does in a transaction, our article on buying a home without your own agent explains the distinction, even though that particular guide is written around Virginia transactions.
How Salyer Wilmoth Homes Approaches a Moyock or Currituck New-Build Purchase
The job is not simply to accompany a buyer through the model home.
Before the contract is signed, I want to understand the buyer's actual finished-house budget, not just the advertised starting price.
Then we identify which contract structure the builder is using and what money becomes committed at each stage.
We compare the lot premium and selected options with comparable properties and the buyer's long-term plans rather than assuming every upgrade is automatically worth the cost.
We make sure the lender sees the developing contract price and understands the projected timeline.
We identify which inspections the contract allows and schedule the buyer's independent inspection process early enough to be useful.
If the property involves septic, private utilities, floodplain concerns, private roads, or unusual lot conditions, those investigations need to be coordinated with the right county office or licensed professional rather than treated as generic builder questions.
And when incentives are offered, we compare the financial result—not just the headline credit.
For buyers relocating from Hampton Roads, there is another layer: the house may only be a few miles farther south, but the contract and closing structure are North Carolina's. Our broader Virginia vs. Northeast North Carolina homebuying-process guide is useful for that background; this article intentionally goes further into the builder-specific decisions instead of repeating those state-line differences.
The goal is straightforward:
By the time you sign, you should know what is being built, what it will actually cost, when your money becomes exposed, what could change the timeline, what you can inspect, and what happens if the finished product or financing does not unfold the way you expected.
Frequently Asked Questions
What should I check before signing a new-construction contract in North Carolina?
Start with the actual contract and attached plans and specifications rather than the model home or marketing sheet. Confirm the finished purchase price, lot premium, included features, allowances, change-order process, earnest money or construction fees, financing provisions, inspection rights, projected completion provisions, warranty, HOA obligations, utilities, road status, and what happens if either side cannot perform. The current NC REALTORS® new-construction form was specifically designed to document many of these issues, but builders may use different agreements, so buyers should obtain legal advice from a North Carolina real estate attorney when they need contract interpretation.
Do I pay a North Carolina due diligence fee when buying new construction?
Not necessarily. A completed or nearly completed new home may be purchased using the ordinary North Carolina Offer to Purchase and Contract with a New Construction Addendum, which can involve the familiar due diligence structure. A home being constructed under Form 800-T instead uses a Pre-Construction Evaluation Period and provides for earnest money and potentially Construction Fees rather than simply mirroring the resale contract. The builder may also use a proprietary agreement. If you are comparing new homes in Moyock, Salyer Wilmoth Homes can help you identify the real-estate implications of the particular structure before you decide how much money you are comfortable committing.
Should I get an independent inspection on a brand-new house?
Yes. North Carolina Real Estate Commission guidance specifically recommends home inspections even for newly constructed homes. County building inspections and the Certificate of Occupancy are important, but they do not replace a buyer's independent inspection. Depending on construction stage and contractual access, a buyer may consider inspections during construction and again near completion.
Can builder upgrades or a lot premium cause an appraisal problem?
They can contribute to a gap between the contract price and the lender's appraised value because buyers should not assume that every dollar spent on upgrades or a preferred lot will be recognized dollar-for-dollar in the appraisal. The lender's appraiser independently develops the value conclusion, and the contractual consequences of a low appraisal depend on the agreement and financing structure. Buyers adding substantial options should keep the lender informed of the changing price and understand what would happen if the completed home's valuation comes in below the amount they agreed to pay.
Is the builder's preferred-lender incentive always the best financing deal?
No. It may be an excellent deal, but buyers should compare it. The CFPB specifically advises new-construction buyers that they are not required to use a builder's associated lender and recommends shopping mortgage options. A large closing-cost credit can look attractive while the underlying interest rate, points, lender charges, or long-term cost differ from another offer. If you are evaluating a builder incentive in Moyock or Currituck County, we can help you keep the real-estate numbers organized while your lenders provide and explain the competing loan terms.
Buying new construction can give you something a resale home often cannot: the opportunity to choose the home, lot, and finishes before anyone else has lived there. But that advantage is most useful when you know exactly what the builder is promising and exactly what you are committing to in return. If you are comparing communities, lots, builder incentives, or contracts in Moyock or elsewhere in Currituck County, Salyer Wilmoth Homes can help you evaluate the real-estate side of the purchase before the exciting decisions become expensive assumptions.
This article provides general real-estate information and is not legal, lending, appraisal, inspection, engineering, tax, insurance, construction, or warranty advice. Builder contracts, deposit terms, financing protections, warranties, association obligations, construction schedules, and property conditions vary by transaction. Buyers should consult the appropriate North Carolina attorney, lender, licensed inspector, appraiser, insurance professional, contractor, county department, and other qualified advisers regarding their specific purchase.
Michele Salyer, REALTOR®
Salyer Wilmoth Homes Team
Atlantic Sotheby’s International Realty
4416 Expressway Drive
Virginia Beach, VA 23452
757-502-3671
michele@salyerwilmothhomes.com
www.salyerwilmothhomes.com
Virginia Real Estate License #0225238875
North Carolina Real Estate License #322300
Equal Housing Opportunity
Considering New Construction in Moyock or Currituck?
From pre-approval to closing day, we guide buyers through every step of the coastal purchase process.
Comments
Be the first to comment.