Cash Offer vs. Financed Offer: What Should Hampton Roads Sellers Compare?
TL;DR
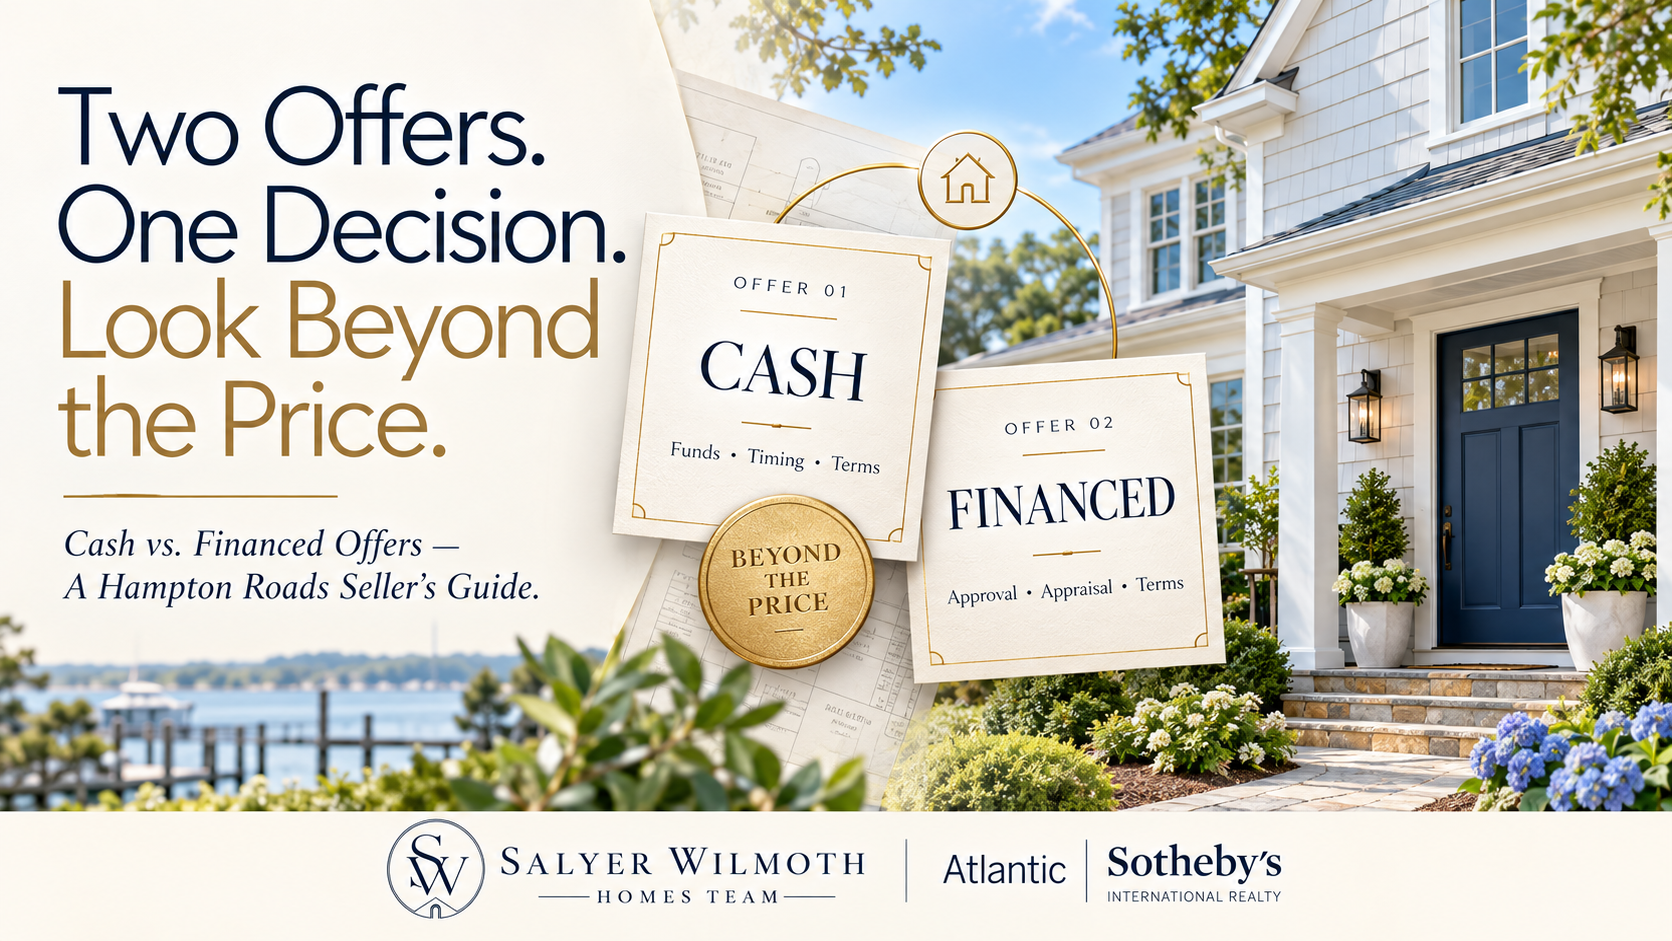
When comparing a cash offer with a financed offer on a Hampton Roads home, sellers should evaluate more than the purchase price. A cash offer may eliminate the buyer's need for mortgage approval and a lender-required appraisal, potentially simplifying the transaction and allowing a shorter closing timeline, but it is not automatically more reliable or financially advantageous. Sellers still need to verify that the buyer has sufficient accessible funds, review any inspection or other contingencies, and determine whether the proposed settlement date is realistic. A financed offer may provide a higher purchase price and stronger net proceeds, especially when the buyer has completed substantial lender verification, offers reasonable contingency terms, and has sufficient funds for the down payment and other obligations. However, financing and appraisal conditions can introduce additional uncertainty, and a preapproval letter does not guarantee final loan approval. Sellers in Virginia Beach, Chesapeake, Norfolk, Portsmouth, Suffolk, Hampton, Newport News, and surrounding Hampton Roads communities should compare verified financial qualifications, appraisal exposure, inspection terms, earnest money, requested concessions, settlement timing, and estimated net proceeds before choosing an offer. The strongest offer is the one that best satisfies the seller's financial and timing objectives while presenting contractual risks the seller is comfortable accepting—not necessarily the highest price or the word “cash” at the top of a contract.
Is a Cash Offer Better Than a Financed Offer When Selling a House?
Not necessarily. A cash offer removes certain mortgage-related steps, but a financed offer may provide better financial terms and a closing schedule that works just as well for the seller.
The decision depends on what each buyer is actually offering and how the proposed transaction would work.
Consider a seller in Chesapeake who receives two offers on the same property.
The first buyer proposes a cash purchase at a slightly lower price, with no financing contingency and a relatively short settlement period.
The second buyer offers more money using mortgage financing, has a lender preapproval, and requests additional time for closing.
The cash offer may be attractive because the transaction does not depend on the buyer obtaining a mortgage. However, the financed offer might produce more money after expenses and concessions.
Neither offer should be accepted or rejected based on its financing label alone.
The National Association of REALTORS® consumer guide to multiple offers explains that price, financial terms, contingencies, earnest money, and closing timing all influence an offer's attractiveness.
For a Hampton Roads seller, I would want to compare those terms side by side before making a recommendation. A slightly higher price can lose some of its appeal if the buyer requests substantial credits or creates uncertainty about the closing. A cash offer can also become less appealing if the buyer has unverified funds or insists on terms that do not meet the seller's needs.
The important question is what the entire contract offers—not which buyer has the more appealing headline.
What Is the Actual Difference Between a Cash Offer and a Financed Offer?
A cash offer generally means the buyer proposes to purchase the property without making the transaction dependent on obtaining mortgage financing.
A financed offer involves a buyer using a mortgage or another approved lending arrangement to fund some portion of the purchase.
That difference can affect the process between contract ratification and closing.
| What to compare | Cash offer | Financed offer |
|---|---|---|
| Mortgage approval | Usually not required to complete the purchase | Generally requires lender approval |
| Proof of financial ability | Verify sufficient available funds | Review lender documentation and available funds |
| Appraisal | No lender-required mortgage appraisal | Lender valuation requirements may apply |
| Financing contingency | Generally absent | May be included, depending on contract |
| Inspection contingency | May still apply | May still apply |
| Closing timeline | May be shorter | Must accommodate lender processing and other requirements |
| Seller concessions | May still be requested | May be requested, subject to financing rules |
| Closing certainty | Depends on funds, contractual terms, and buyer performance | Depends on underwriting, property approval, contractual terms, and buyer performance |
The table describes typical differences, not promises about a specific transaction.
A cash buyer may still request a property appraisal for personal information, inspect the home, investigate title, or make the purchase dependent on another transaction.
A financed buyer may have very limited contract contingencies and substantial verified funds.
The written purchase agreement determines which obligations and protections apply.
That is why a seller should review each offer as a distinct contractual proposal rather than assume one transaction structure is automatically safer.
How Can Sellers Verify That a Cash Buyer Actually Has the Funds?
A cash offer is only as credible as the buyer's documented ability to complete the purchase.
Before accepting a cash offer, sellers should request appropriate verification that the buyer has sufficient funds available to fulfill the proposed agreement.
Proof of funds may take the form of an appropriately dated financial-institution statement or a letter from an institution holding the buyer's assets, depending on the contract's requirements.
It should establish that sufficient assets exist and that they can be made available for settlement.
A buyer's statement that they have money, without acceptable supporting documentation, is not equivalent to verification.
Virginia REALTORS® has addressed this distinction in its guidance on proof-of-funds requirements, explaining that an advisor's belief that a buyer has sufficient assets may not satisfy contract language requiring confirmation from a third party in possession of those assets.
Sellers should also distinguish available cash from assets that still require additional steps before they can be used.
For example, a buyer may have sufficient investment holdings but need time to liquidate them. Another may expect proceeds from the sale of another property.
The source and accessibility of the funds can affect the closing schedule.
The buyer should not be asked to disclose unnecessary private financial information. The relevant information can often be verified while protecting unrelated account details.
The exact proof-of-funds deadline, acceptable evidence, and consequences of noncompliance depend on the form and provisions of the executed purchase agreement.
If a cash offer is being presented as especially attractive because it can close quickly, I would want sufficient documentation to support that claim before treating the proposed timeline as realistic.
How Strong Is a Financed Buyer's Mortgage Preapproval?
A preapproval letter can be helpful, but it is not a guarantee that the buyer will receive a mortgage.
The Consumer Financial Protection Bureau explains that mortgage preapproval represents a lender's tentative willingness to extend credit based on information and assumptions reviewed during the process.
The scope of that review varies.
Some lenders may have verified important details about the borrower's income, assets, and credit. Others may still need substantial documentation before underwriting can be completed.
The label on the letter does not establish exactly how thoroughly the applicant has been reviewed.
Sellers should ask appropriate transaction-focused questions through their agent, including whether the lender has reviewed income and assets, whether the proposed financing is consistent with the purchase amount, and whether significant underwriting requirements remain outstanding.
Any request for lender clarification should respect the buyer's privacy and applicable lending requirements.
The buyer's available funds also matter.
A financed offer with a substantial down payment may involve different financial considerations from one using a smaller down payment, but the size of the down payment alone is not proof of overall creditworthiness or closing certainty.
An offer may depend on underwriting conditions, the property appraisal, lender documentation, and the buyer continuing to satisfy loan requirements through settlement.
Our separate article on what happens if a buyer's financing falls through before closing explains the complications that may arise after financing problems develop.
During offer evaluation, the purpose is to understand which issues have already been addressed and what remains to be completed.
Why Does the Financing Contingency Matter?
A financing contingency can affect the buyer's contractual rights if the proposed mortgage is not approved.
However, sellers should not assume every financed offer contains identical financing protections.
The wording, deadlines, notice requirements, and conditions are determined by the signed agreement and any applicable addenda.
Some financing contingencies may permit the buyer to terminate under specified circumstances if financing cannot be obtained, provided the required steps and notices are completed.
Other contract provisions may affect the buyer's obligations even when financing becomes uncertain.
A seller should understand the difference between a lender declining the loan and the purchase agreement allowing the buyer to terminate without contractual consequences.
Those are separate questions.
Before accepting a financed offer, review the financing terms with particular attention to the loan program, approval requirements, applicable deadlines, buyer obligations, and any conditions that could affect settlement.
A buyer who is making progress toward approval may still encounter a late underwriting issue.
However, the existence of a financing contingency does not make a financed contract inherently unacceptable.
The relevant decision is whether its protections and deadlines are reasonable in light of the offer's other terms.
How Does Appraisal Risk Affect the Comparison?
Appraisal exposure is one of the most meaningful differences between many cash and financed offers.
A mortgage lender generally requires an acceptable property valuation before funding a residential purchase, although the particular method of valuation can vary.
If the lender's valuation is below the contract price, the amount available through financing may be affected.
Consider a Virginia Beach home under contract for $510,000.
If the lender's acceptable valuation is only $495,000, the buyer may need additional funds, a revised loan structure, or a negotiated price adjustment, depending on the applicable loan program and contract.
That does not automatically require the seller to reduce the price.
It also does not automatically establish that the buyer can terminate the agreement without consequences.
The outcome depends on the appraisal provisions, financing terms, lender requirements, and any applicable protections associated with the loan program.
Our article on what happens when a Virginia home appraises below the offer price explains the available considerations in greater detail.
For an offer comparison, the seller should identify whether an appraisal contingency exists and what happens if the lender's valuation is below the contract price.
A buyer offering to contribute additional funds toward an appraisal shortfall should have an appropriate basis for demonstrating that those funds are available.
The absence of a separate appraisal contingency does not automatically eliminate every lender-related valuation requirement or contractual protection.
A cash buyer generally avoids the need for a lender's mortgage appraisal, but can still request their own independent valuation or include an appraisal-related condition.
The seller should focus on the exact written terms.
Can a Financed Offer With an Appraisal Contingency Still Be Attractive?
Yes.
An appraisal contingency is one factor in the transaction, not a complete measure of the buyer's ability to perform.
A financed buyer may offer a price supported by recent comparable sales, have substantial verified funds, and provide a settlement timeline that aligns with the seller's plans.
Such an offer may be more appealing than a lower cash proposal with unfavorable inspection terms or uncertain access to funds.
The property's likely market value is important.
If the proposed price is materially above the supportable range indicated by comparable sales, a seller should understand that risk before treating the additional amount as money they will definitely receive.
This is particularly relevant when multiple offers are being submitted for the same home.
An aggressive offer price can look compelling, but if the buyer depends on a lender valuation and has limited funds to address a shortfall, the seller may face a renegotiation later.
At Salyer Wilmoth Homes, we would examine the proposed price against the available comparable sales and the home's actual condition before treating the offer amount as fully achievable.
The point is not to predict a specific appraisal result. It is to identify how much of the purchase price may depend on assumptions that have not yet been verified.
Why Do Inspection Terms Matter Even With a Cash Buyer?
A cash offer does not automatically eliminate inspections, repair negotiations, or other property-condition concerns.
A buyer paying cash may request a general home inspection, specialized inspections, or a contractual right to evaluate the property before continuing.
The seller should review the scope of the inspection provisions, applicable deadlines, and what options the buyer has if an issue is discovered.
For example, a cash buyer who requests a broad inspection contingency with an extended decision period may introduce more uncertainty than a financed buyer who proposes a narrower and shorter inspection arrangement.
That does not mean the seller should automatically prefer the financed offer.
It means inspection terms should be considered independently from the financing method.
Sellers should also pay attention to any proposed repair obligations.
An offer that initially appears strong can have a different financial effect if the parties later negotiate substantial repairs or credits.
Our guide to home inspection surprises in Hampton Roads addresses the kinds of issues buyers may investigate and how those findings can affect negotiations.
When reviewing competing offers, the seller should understand which inspection rights each buyer is requesting rather than assume that a cash offer means an inspection-free sale.
What Does Earnest Money Tell a Seller About an Offer?
An earnest-money deposit shows that the buyer is committing an agreed amount of money under the purchase contract.
The deposit can be relevant when comparing offers, but it does not guarantee that the transaction will close.
It also should not be treated as additional proceeds on top of the agreed purchase price.
When the sale closes, earnest money is generally credited toward the buyer's payment obligations.
If the contract does not close, entitlement to the deposit depends on the agreement, the circumstances, and any applicable dispute-resolution requirements.
For a seller comparing two offers, a larger earnest-money deposit may provide information about the buyer's willingness to commit funds, but it does not independently resolve financing, appraisal, or inspection risks.
The seller should examine the deposit amount together with the deadlines and circumstances under which the buyer may be entitled to its return.
An offer with a large deposit but broad termination protections may not be as different from another offer as the deposit amount initially suggests.
Do not assume that the seller automatically keeps the deposit if the buyer changes plans or fails to obtain financing.
The actual contract language controls the available remedies and deposit procedures.
How Should Sellers Compare Closing Dates?
A shorter closing date can be advantageous, but only if it is achievable and consistent with the seller's plans.
A cash buyer may be able to avoid mortgage underwriting and related lender processes. That can make a shorter transaction possible.
However, the sale may still require title examination, settlement preparation, payoff information, required documentation, and coordination among the parties.
A cash offer proposing settlement in an unusually short period should be supported by available funds and confirmation that the necessary closing professionals can accommodate the schedule.
A financed buyer generally needs enough time for underwriting, valuation, required disclosures, and final lending approval.
The seller should consider whether the proposed lender and settlement schedule is realistic.
The closing date should also be evaluated against the seller's own circumstances.
For example, a Suffolk homeowner purchasing another property may prefer a particular settlement date because of the timing of their next purchase.
A faster offer is not necessarily better when it creates an unnecessary move, requires interim housing, or disrupts a related transaction.
Our article on what happens after accepting an offer in Hampton Roads explains the contract-to-closing steps that begin once an agreement is ratified.
The best closing date is one the buyer can reasonably meet and the seller can comfortably accommodate.
How Do You Compare Actual Seller Net Proceeds?
Offer price and seller net proceeds are not the same thing.
A seller's final proceeds depend on the purchase price, mortgage payoff, brokerage compensation, negotiated credits, settlement expenses, applicable transfer-related charges, prorations, and other obligations associated with the particular transaction.
When comparing two offers, the first step is to subtract the concessions requested by each buyer and then prepare a transaction-specific net estimate.
Consider this simplified hypothetical comparison for a Hampton Roads property.
| Offer terms | Cash buyer | Financed buyer |
|---|---|---|
| Offered purchase price | $505,000 | $520,000 |
| Requested seller closing-cost credit | $0 | $12,000 |
| Price less proposed credit | $505,000 | $508,000 |
| Proposed closing period | 21 days | 40 days |
| Financing contingency | None | Included |
| Lender appraisal requirement | None | Subject to lender requirements |
| Inspection contingency | Included | Included |
In this example, the financed offer provides $3,000 more after the specified credit, before accounting for other selling expenses, tax differences, adjustments, and any subsequent negotiations.
That $3,000 difference is the starting point for a conversation—not an automatic reason to accept the financed offer.
The seller should consider whether the additional expected proceeds justify the financing and appraisal exposure, longer closing period, and actual contract conditions.
If the financed buyer has strong lender documentation, reasonable deadlines, and adequate funds, the additional proceeds may be attractive.
If the seller needs a shorter settlement and the cash buyer has verified funds with satisfactory terms, the lower cash offer may align more closely with the seller's priorities.
For a more complete estimate, the settlement professional should calculate the relevant expenses.
Our guide to Virginia Beach seller closing costs and tax stamps explains how transfer-related charges affect the final amount received at closing.
The most useful comparison is an offer-specific seller net sheet, paired with an assessment of the conditions that could affect whether that amount is ultimately received.
What If One Offer Requests a Seller Credit or Rate Buydown?
A financed buyer may request the seller to contribute toward eligible closing costs, prepaid expenses, discount points, or an approved mortgage rate buydown.
A cash buyer may also request credits or other negotiated concessions, although mortgage-program limits would not apply in the same way when no mortgage is involved.
The seller should calculate the financial effect of each request rather than focus only on the purchase price.
For example, a $520,000 offer requesting a $12,000 credit should not be compared directly with a $505,000 offer requesting no credit.
The seller should compare the resulting proceeds and determine whether the higher proposed price is supportable.
For a financed transaction, the buyer's lender must confirm the allowable contribution and its treatment under the financing program.
A higher contract price designed to offset concessions may introduce appraisal concerns.
Our separate article on price reductions versus closing-cost credits explains the strategic difference between these two tools.
During offer selection, however, the immediate question is simpler: What is the buyer asking the seller to pay, and how does that affect the amount the seller can expect to receive?
Does a Cash Offer Always Have Greater Closing Certainty?
No.
A cash offer can remove certain mortgage-related uncertainties, but it does not eliminate all possible reasons for delay or nonperformance.
The buyer may fail to provide acceptable financial verification, encounter delays accessing the funds, request further inspections, or fail to complete contractual obligations.
A cash transaction may also be subject to other conditions written into the offer.
A financed buyer may have already completed substantial financial verification and may be working with a lender capable of meeting the proposed timeline.
Neither situation can be reduced to a universal guarantee.
Closing certainty depends on the combination of verified financial ability, the property's readiness for transfer, contractual deadlines, and the parties' ability to complete their obligations.
A seller should be especially careful with a cash offer that depends on funds from another property sale, a pending transfer, or an investment transaction that has not yet been completed.
Those circumstances may be perfectly workable, but they should be evaluated honestly rather than treated as equivalent to immediately available funds.
The purpose of reviewing documentation is to identify uncertainty early—not to assume every buyer using a particular financing method presents the same level of risk.
How Should Sellers Evaluate Offers Fairly and Objectively?
Virginia sellers should compare offers using legitimate transaction factors, such as proposed price, documented financial ability, contractual contingencies, requested concessions, earnest money, and settlement timing.
Virginia's Fair Housing Law protects against discrimination based on specified characteristics, including source of funds.
The law's protections mean sellers and their agents should not use blanket assumptions about an individual buyer or automatically exclude a financing category without considering the applicable legal requirements.
Virginia REALTORS® has specifically cautioned against refusing to consider VA-financed offers merely because they use VA financing.
At the same time, competing offers can have objectively different financial terms, appraisal protections, deadlines, and closing requirements.
Those contract differences may be relevant when determining which proposal meets the seller's goals.
For example, comparing the amount of available funds, the presence of an appraisal contingency, and the feasibility of settlement is different from making assumptions about a buyer based on military status, household composition, or another protected characteristic.
The Virginia Fair Housing Law provides the governing framework, while Virginia REALTORS® offers additional professional guidance about evaluating multiple offers.
The objective is to make an informed, lawful decision based on the actual offer and the seller's legitimate needs.
What Should You Do When Two Offers Are Close?
When the financial difference is relatively small, the nonprice terms deserve closer attention.
Ask what matters most in the transaction.
Is the seller trying to maximize net proceeds? Coordinate another purchase? Avoid significant uncertainty? Complete a sale by a particular date?
The answers help determine which terms deserve the most weight.
A seller may also consider making a counteroffer to address an unfavorable condition.
For example, a buyer offering a favorable price might agree to adjust an inspection deadline, clarify the financing provisions, or change the settlement date.
However, a counteroffer has legal consequences, and sellers should not assume that an offer previously received remains available indefinitely.
The seller's agent should explain the negotiation choices and coordinate with legal counsel when contract interpretation is necessary.
The National Association of REALTORS® advises sellers to consider the risks of different multiple-offer strategies, including accepting one proposal, countering, or requesting improved terms from competing buyers.
No strategy guarantees that the buyers will maintain or improve their original offers.
A seller should avoid accepting one agreement and attempting to substitute another without appropriate legal guidance.
The better approach is to understand the competing offers thoroughly before becoming contractually committed.
How Salyer Wilmoth Homes Helps Sellers Compare Competing Offers
When a seller receives more than one offer, our role is to make the financial and contractual differences understandable before the seller makes a decision.
We would begin by identifying the seller's priorities, including desired proceeds, preferred closing timing, relocation plans, and tolerance for conditions that could delay the transaction.
Then we would prepare a side-by-side comparison of the proposed terms.
The comparison would address purchase price, requested seller credits, proposed financing, proof of funds or lender documentation, appraisal provisions, inspection rights, earnest money, and important contractual deadlines.
For financed offers, we would review the available lender information and coordinate appropriate questions about unresolved approval conditions.
For cash offers, we would request relevant verification of the funds and determine whether the proposed settlement date is supported by the transaction's requirements.
We would also compare the proposed contract prices with available local sales evidence to identify potential appraisal concerns without pretending to predict the outcome of a lender's valuation.
On the financial side, we would develop an estimated seller net for each proposal and work with the settlement professional when more precise figures are required.
If the seller wants to negotiate, we would help evaluate which terms could be adjusted and what tradeoffs those changes might create.
Once an offer is accepted, we would coordinate the real-estate aspects of contract deadlines and communication among the buyer's agent, lender, settlement professional, and other parties.
We would not guarantee loan approval, certify the authenticity of financial assets independently, or provide legal opinions about contractual remedies.
Those determinations belong to the appropriate qualified professionals.
The goal is to help sellers make a decision using the strongest available information about financial outcomes, contract terms, and practical closing requirements—not an unsupported assumption that the highest or fastest offer must be the best.
Frequently Asked Questions
Is a cash offer better than a financed offer when selling a house?
Not always. A cash offer may eliminate mortgage approval requirements and a lender-required appraisal, potentially simplifying the sale. However, sellers should verify that the funds are available and evaluate any inspection, title, or other contractual conditions. A financed offer may provide stronger net proceeds and acceptable timing when the buyer has reliable lender documentation and reasonable contingencies. The stronger proposal depends on the seller's priorities and the complete terms of each offer, not simply the financing method.
What proof of funds should a cash homebuyer provide?
A cash buyer should provide documentation that satisfies the purchase agreement's requirements and demonstrates sufficient accessible funds for the transaction. Depending on the contract, this may include an appropriate financial-institution statement or verification from a third party holding the assets. A general statement from someone who believes the buyer has sufficient money may not meet the contract's requirements. If you are evaluating a cash offer on a Hampton Roads home, Salyer Wilmoth Homes can help coordinate the appropriate documentation request and review the related offer terms.
Can a financed offer be stronger than a cash offer?
Yes. A financed offer may provide greater expected net proceeds, more favorable inspection terms, or a settlement date that better fits the seller's plans. Its attractiveness also depends on the buyer's documented financing progress, appraisal provisions, available funds, and contractual protections. A preapproval letter does not guarantee a loan, but a well-supported financed offer should not be dismissed solely because the buyer intends to use mortgage financing. We can help compare the actual terms and prepare estimated seller proceeds for each proposal.
Can a cash buyer still back out after signing a contract?
Potentially, depending on the purchase agreement and the reason for termination. Paying cash does not automatically remove inspection contingencies or other contractual protections. A buyer may also fail to perform without having a valid contractual basis to terminate, which raises separate questions about remedies and earnest money. The outcome depends on the specific contract and applicable law. Sellers should consult their real estate professional and, when necessary, a Virginia attorney before assuming that a cash purchase guarantees closing or an automatic right to retain the deposit.
Should I accept a lower cash offer instead of a higher mortgage offer?
A lower cash offer may be preferable if its verified funds, acceptable contractual conditions, and proposed closing schedule better satisfy your needs. However, a higher financed offer may provide enough additional net proceeds to justify its underwriting and appraisal requirements. Before deciding, compare concessions, relevant deadlines, inspection rights, and the financial strength of each buyer. Salyer Wilmoth Homes can help develop an offer-by-offer net comparison and coordinate questions with the appropriate lending and settlement professionals.
This article provides general real estate information and is not a substitute for advice from a Virginia real estate attorney, mortgage lender, settlement professional, financial adviser, or other appropriately licensed professional. Financing and appraisal requirements, earnest-money rights, fair housing obligations, and contract remedies depend on the specific transaction and applicable law.
If you are selling a home in Virginia Beach, Chesapeake, Norfolk, Portsmouth, Suffolk, Hampton, Newport News, or another Hampton Roads community and want to compare competing offers beyond their purchase prices, Salyer Wilmoth Homes can help evaluate the financial terms, documentation, contingencies, and settlement considerations before you make a decision. Connect with our team to discuss your property and selling priorities.
Michele Salyer, REALTOR®
Salyer Wilmoth Homes Team
Atlantic Sotheby's International Realty
4416 Expressway Drive
Virginia Beach, VA 23452
757-502-3671
michele@salyerwilmothhomes.com
www.salyerwilmothhomes.com
Virginia Real Estate License #0225238875
North Carolina Real Estate License #322300
Equal Housing Opportunity
Compare Your Offers Beyond the Purchase Price
Learn how we position coastal homes to sell for their full value with professional marketing and local expertise.
Comments
Be the first to comment.
Leave a Comment
Related Articles